Three-year fixed home loans lost half of their following among Singapore borrowers in the first nine months of 2026. In an article published on 8 October 2026 and contributed by a mortgage advisory, Stacked Homes reported that the three-year option drew 44% of borrowers in January 2026 but only 22% in September 2026, with the data running to 28 September.
The two-year fixed loan took up the slack. Stacked Homes said its share climbed from 23% to 59% over the same stretch, making it the clear majority choice by the end of the period. Floating loans stayed in the mix as well, pegged either to SORA or to a bank board rate, though the report centred on the swing between the two main fixed terms.
The article also explained why local rates react with a delay. Stacked Homes noted that the Monetary Authority of Singapore manages the Singapore dollar exchange rate rather than interest rates, so SORA tends to move more slowly than its US counterparts. The quick take below sets out the three numbers behind the switch.
- The gap between terms widened. Stacked Homes put the typical accepted two-year fixed rate at 1.45% in January and 1.50% in September 2026. The typical three-year rate began at 1.55% in January, held at 1.70% from June to August and settled at 1.65% in September, so the longer commitment carried a higher cost through the middle of the year.
- Quoted ranges told a similar story. At the time of the report, Stacked Homes listed floating packages at about 1.40% to 1.60%, three-year fixed packages near 1.85% for larger loans and above 2.05% for most typical loans, and five-year fixed packages at about 2.08%.
- The pressure came from abroad and at home. Stacked Homes linked firmer fixed pricing to a US Federal Reserve hike in September 2026, with one more projected before the close of 2026, and to a one-month SORA reading above the three-month compounded figure of about 1.23%, a spread that usually signals upward pressure on floating rates. Banks were already pricing further hikes into packages, the outlet added.
Verdict: the September 2026 figures describe borrowers choosing shorter fixed commitments while lenders priced longer ones more firmly. Stacked Homes also flagged the terms that sit behind any headline rate: a redemption penalty of 1.50% of the amount prepaid, free conversion after 12 months in some packages, and post-lock-in rates that can reset to SORA plus a high spread.
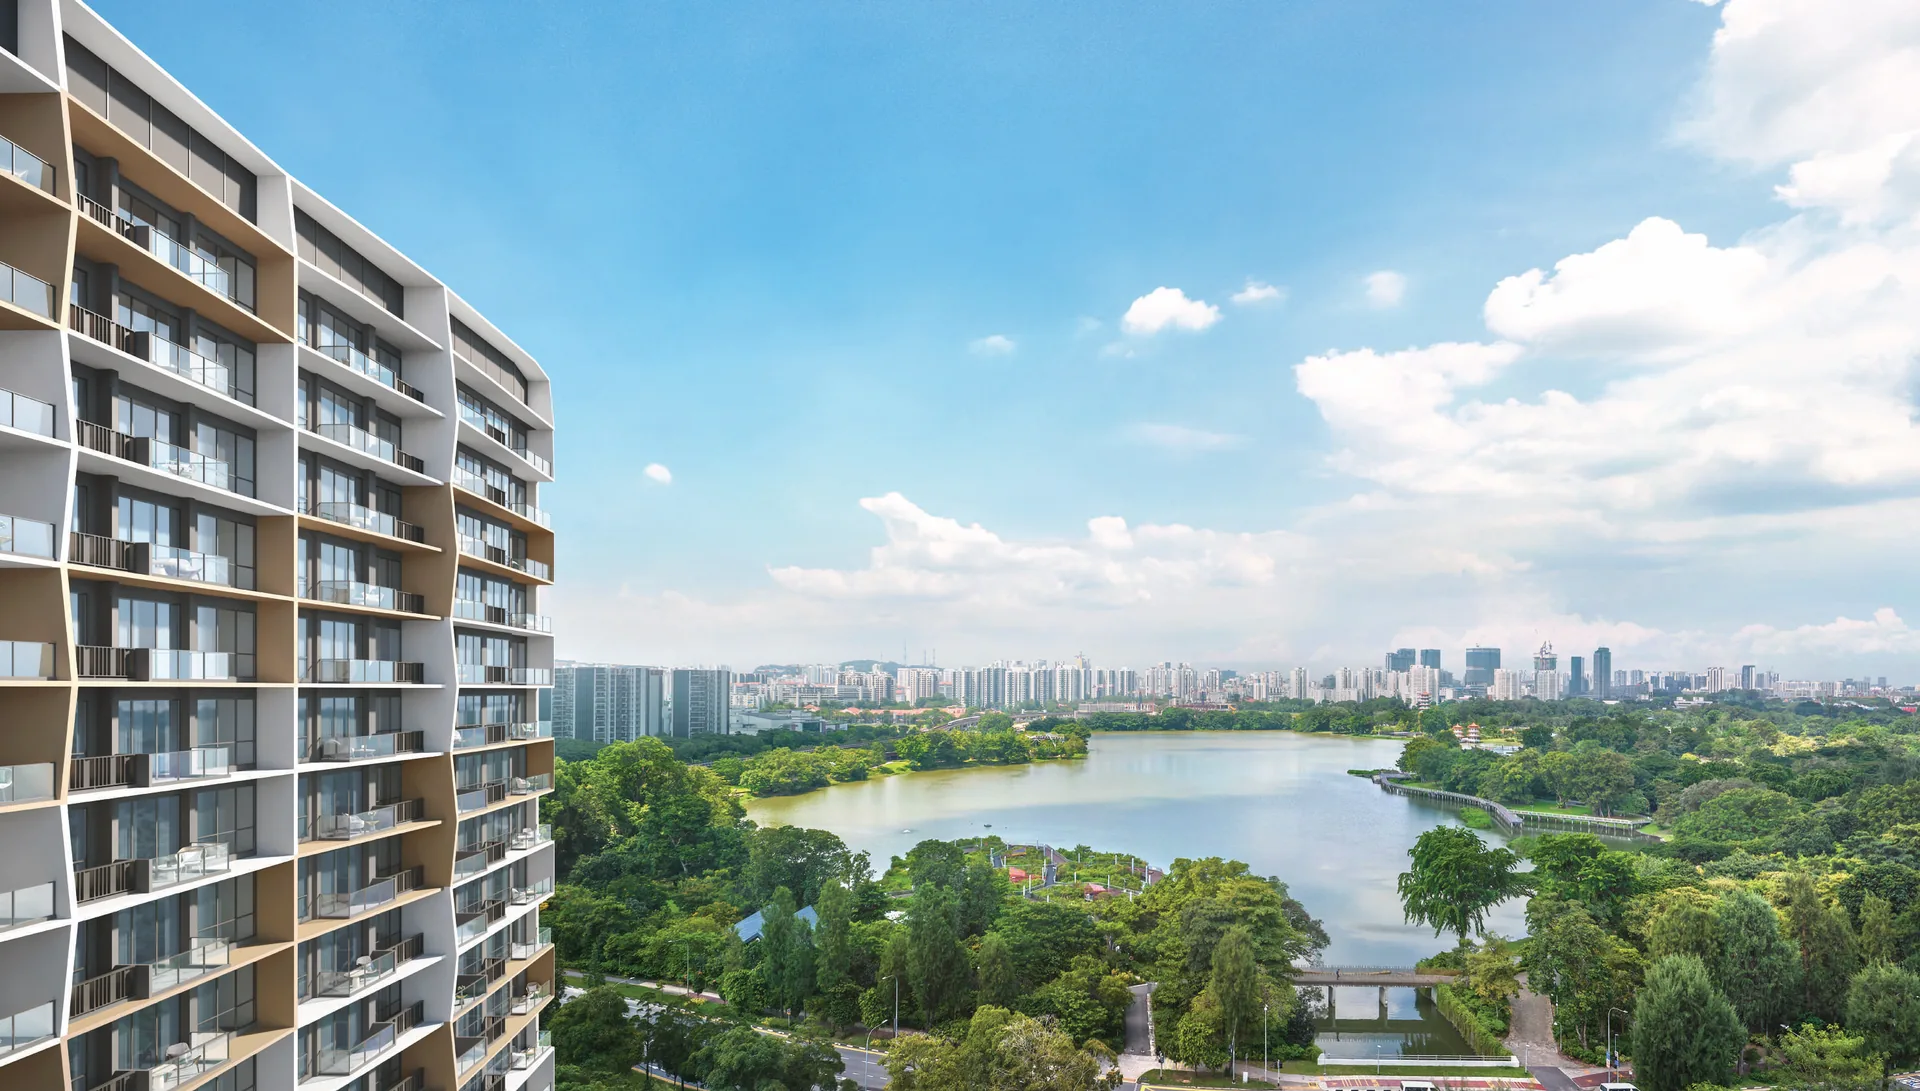
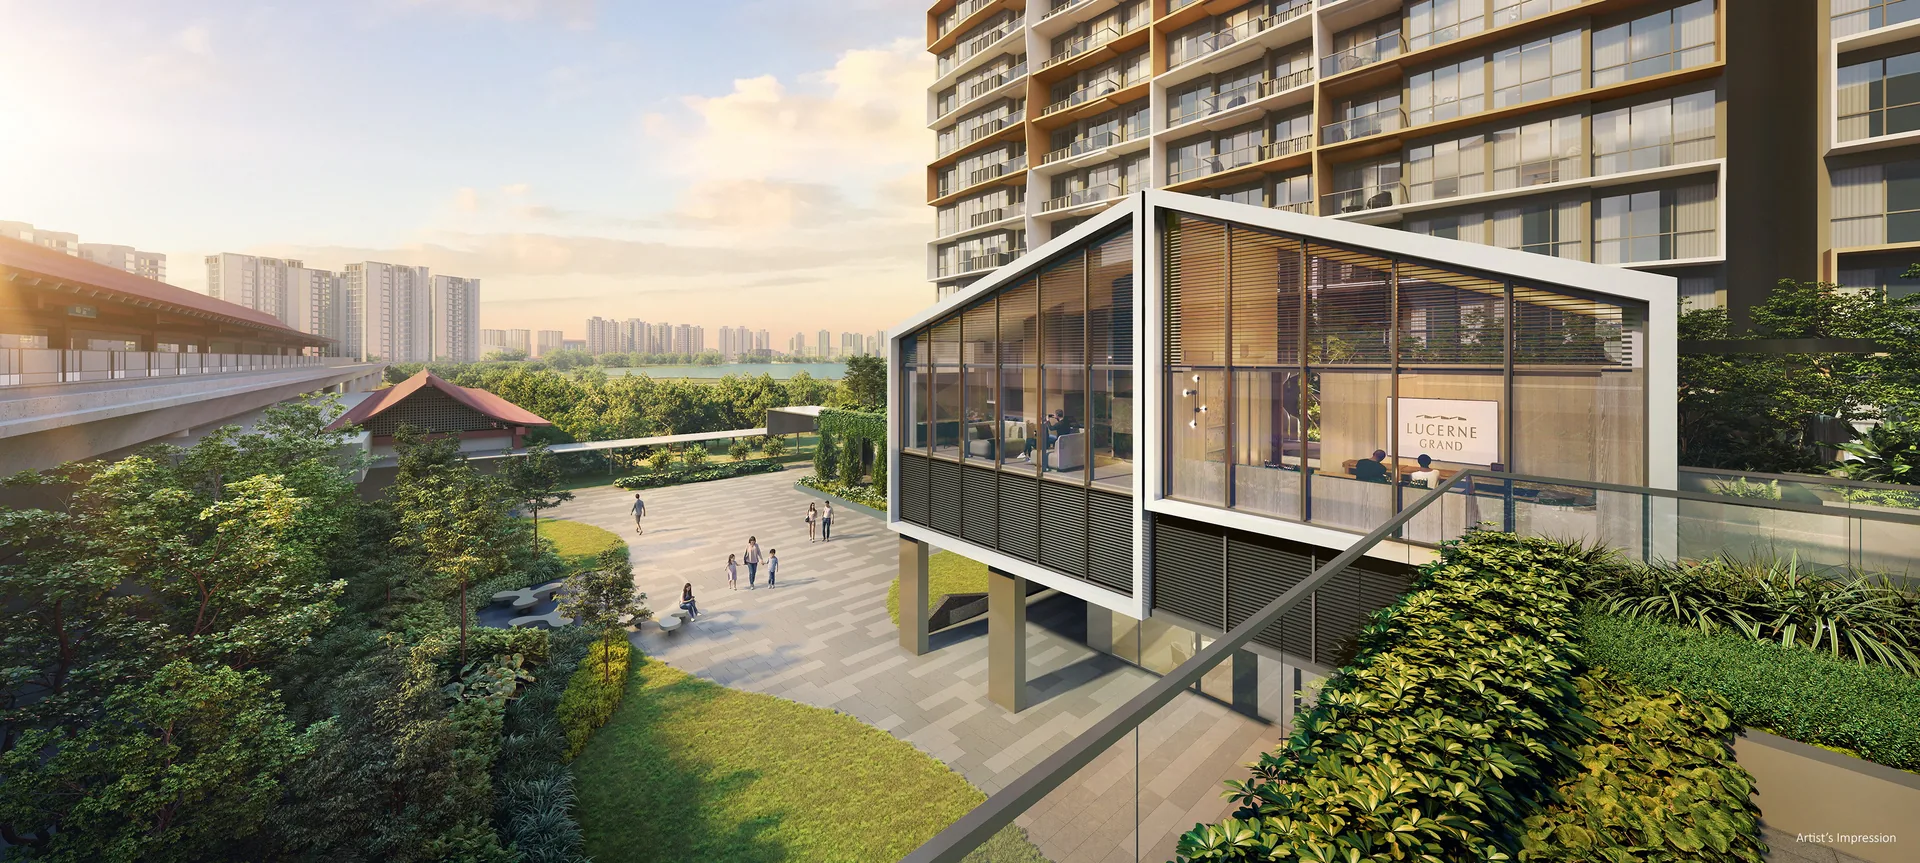
Lucerne Grand opened its sales booking on 3 October 2026, following a preview from 18 September. CDL Polaris Properties Pte. Ltd., a wholly owned subsidiary of City Developments Limited, is developing 570 homes in five 17-storey blocks at 30-38 Lakeside Drive in District 22, from 624 sqft two-bedroom layouts to 1,432 sqft four-bedroom premium units. The site has a direct link to Lakeside MRT (EW26), a 99-year lease from 8 September 2025, Green Mark Platinum Super Low Energy status and expected vacant possession on 7 December 2031.
Booking details and the full unit list are available from the Sales Concierge via the contact page.
Source: Stacked Homes, 8 October 2026 (data as at 28 September 2026).
General information only, not financial or legal advice.
Source: Stacked Homes. This article is independent commentary; Lucerne Grand is not affiliated with the parties mentioned.
Register Your Interest in Lucerne Grand
The e-brochure, the full set of floor plans and the current price list are sent to registered parties by the Sales Concierge. Showflat viewings are arranged by appointment through the Sales Concierge. Registering is free and carries no obligation.
What the Sales Concierge sends
- The Lucerne Grand e-brochure and the full project details.
- All seventeen floor plan types, from the 624 sq ft 2-bedroom to the 1,432 sq ft 4-bedroom premium with entertainment room.
- The current price list and the balance units as they update.
Register Your Interest
Prefer to speak to someone? Call +65 6200 6220, or message the same number on WhatsApp.